
FinzData Weekly · FinzData Research · Published 23 October 2026
FinzData Weekly: Liquidity, Capital Flows & Positioning, October 23, 2026
Liquidity, capital flows and positioning for the week to October 23, 2026, built from the FinzData database. Data, not investment advice.
Get FinzData research free, every morning
The daily brief: what moved, the macro releases that matter, positioning and liquidity, with charts. One email a day, free, unsubscribe anytime.
Contents
- This week in five lines
- Fed net liquidity
- What moved liquidity
- Money and financial conditions
- Foreign capital flows (TIC)
- ETF and crypto flows
- Positioning map
- Most crowded
- Biggest weekly swings
- Every number here is one call to the FinzData API
- Method and sources
1. FinzData Weekly: Liquidity, Capital Flows & Positioning
Cover slide for the FinzData Weekly issue dated October 23, 2026. The deck covers liquidity, capital flows and positioning for the week.
import finzdata as yf

c = yf.Client()

# Net liquidity: Fed assets minus TGA minus reverse repo
liq = c.liquidity("FED_NET_LIQUIDITY")

# COT positioning: S&P 500 futures, TFF report
cot = c.cot(report="tff_fo", market="13874+")

# Treasury International Capital flows
tic = c.tic()
Built for AI, quants, data scientists and financial analysts who backtest. Clean data. Real insights. Real alpha. finzdata.com. This material is for information only and is not investment advice.
2. This week in five lines
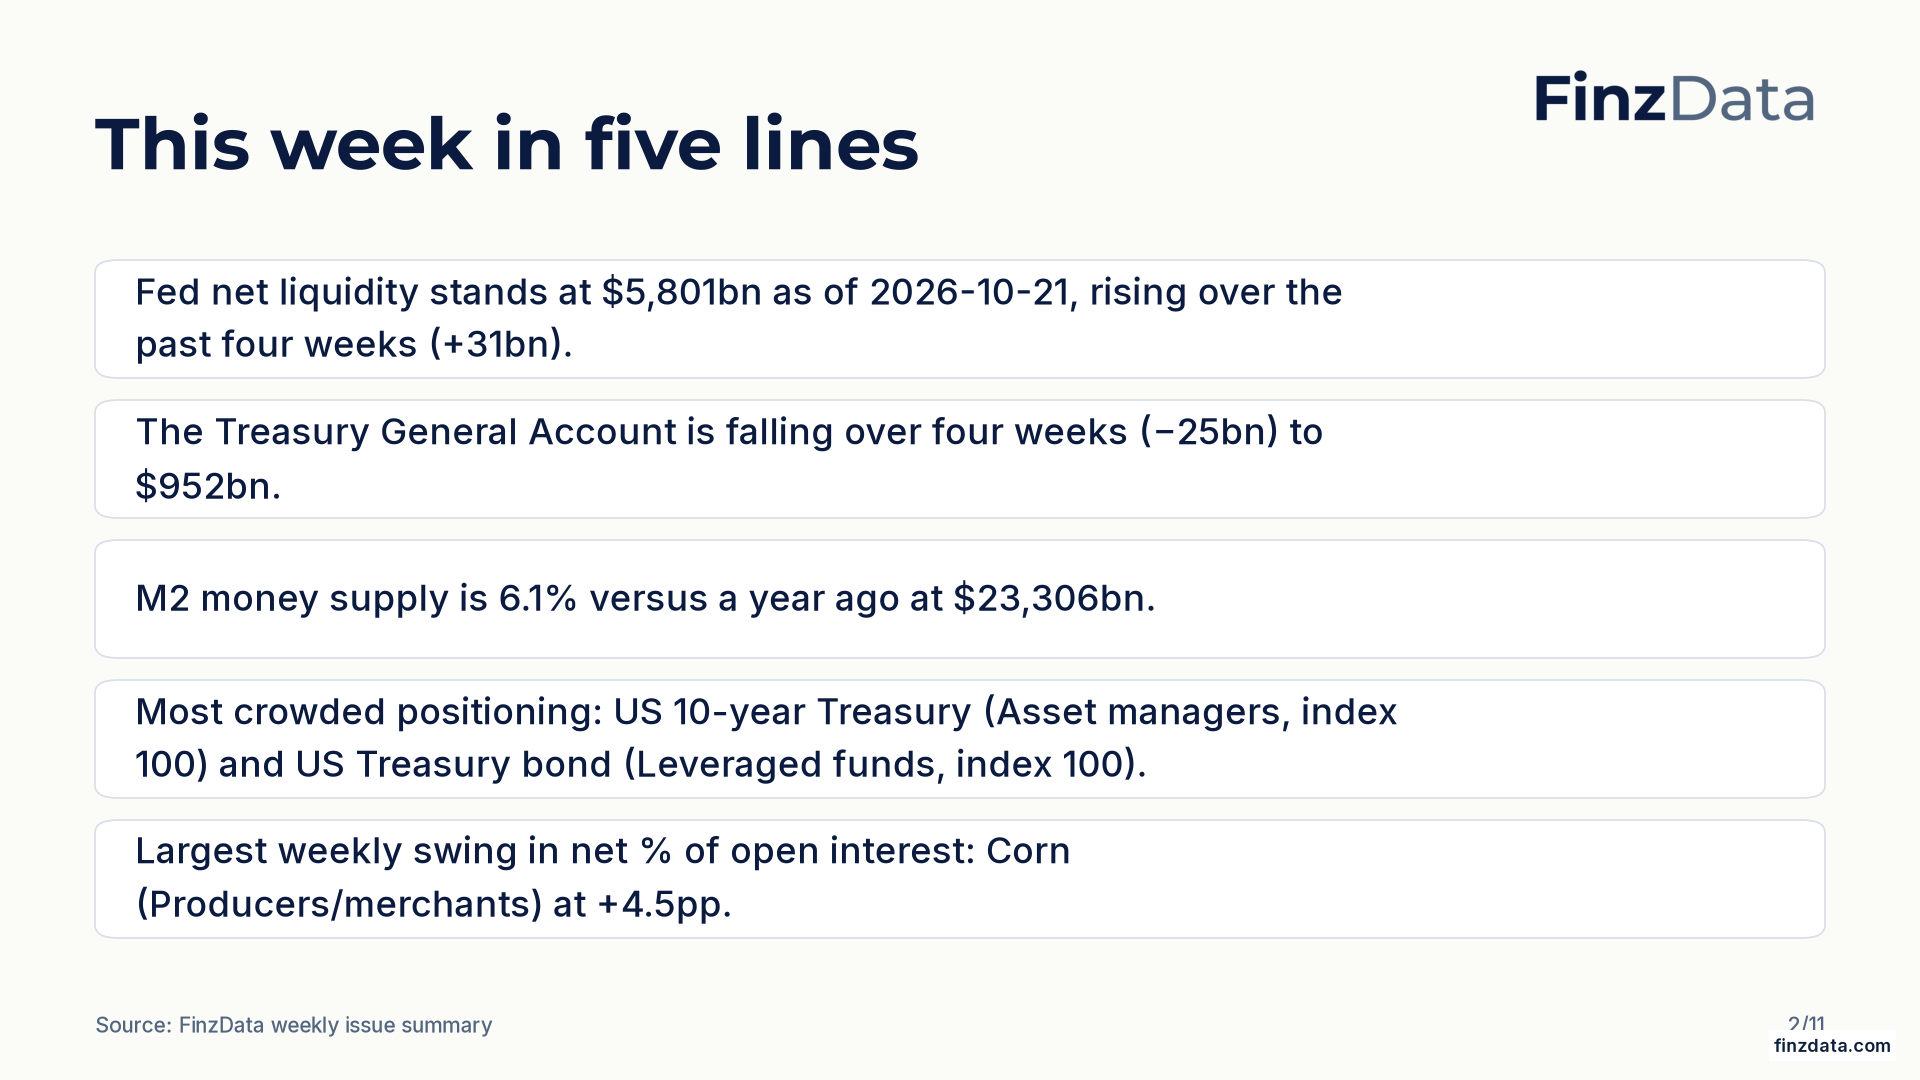
Key takeaways from this week's issue: Fed net liquidity stands at $5,801bn as of 2026-10-21, rising over the past four weeks (+31bn). The Treasury General Account is falling over four weeks (−25bn) to $952bn.
- Fed net liquidity stands at $5,801bn as of 2026-10-21, rising over the past four weeks (+31bn).
- The Treasury General Account is falling over four weeks (−25bn) to $952bn.
- M2 money supply is 6.1% versus a year ago at $23,306bn.
- Most crowded positioning: US 10-year Treasury (Asset managers, index 100) and US Treasury bond (Leveraged funds, index 100).
- Largest weekly swing in net % of open interest: Corn (Producers/merchants) at +4.5pp.
3. Fed net liquidity
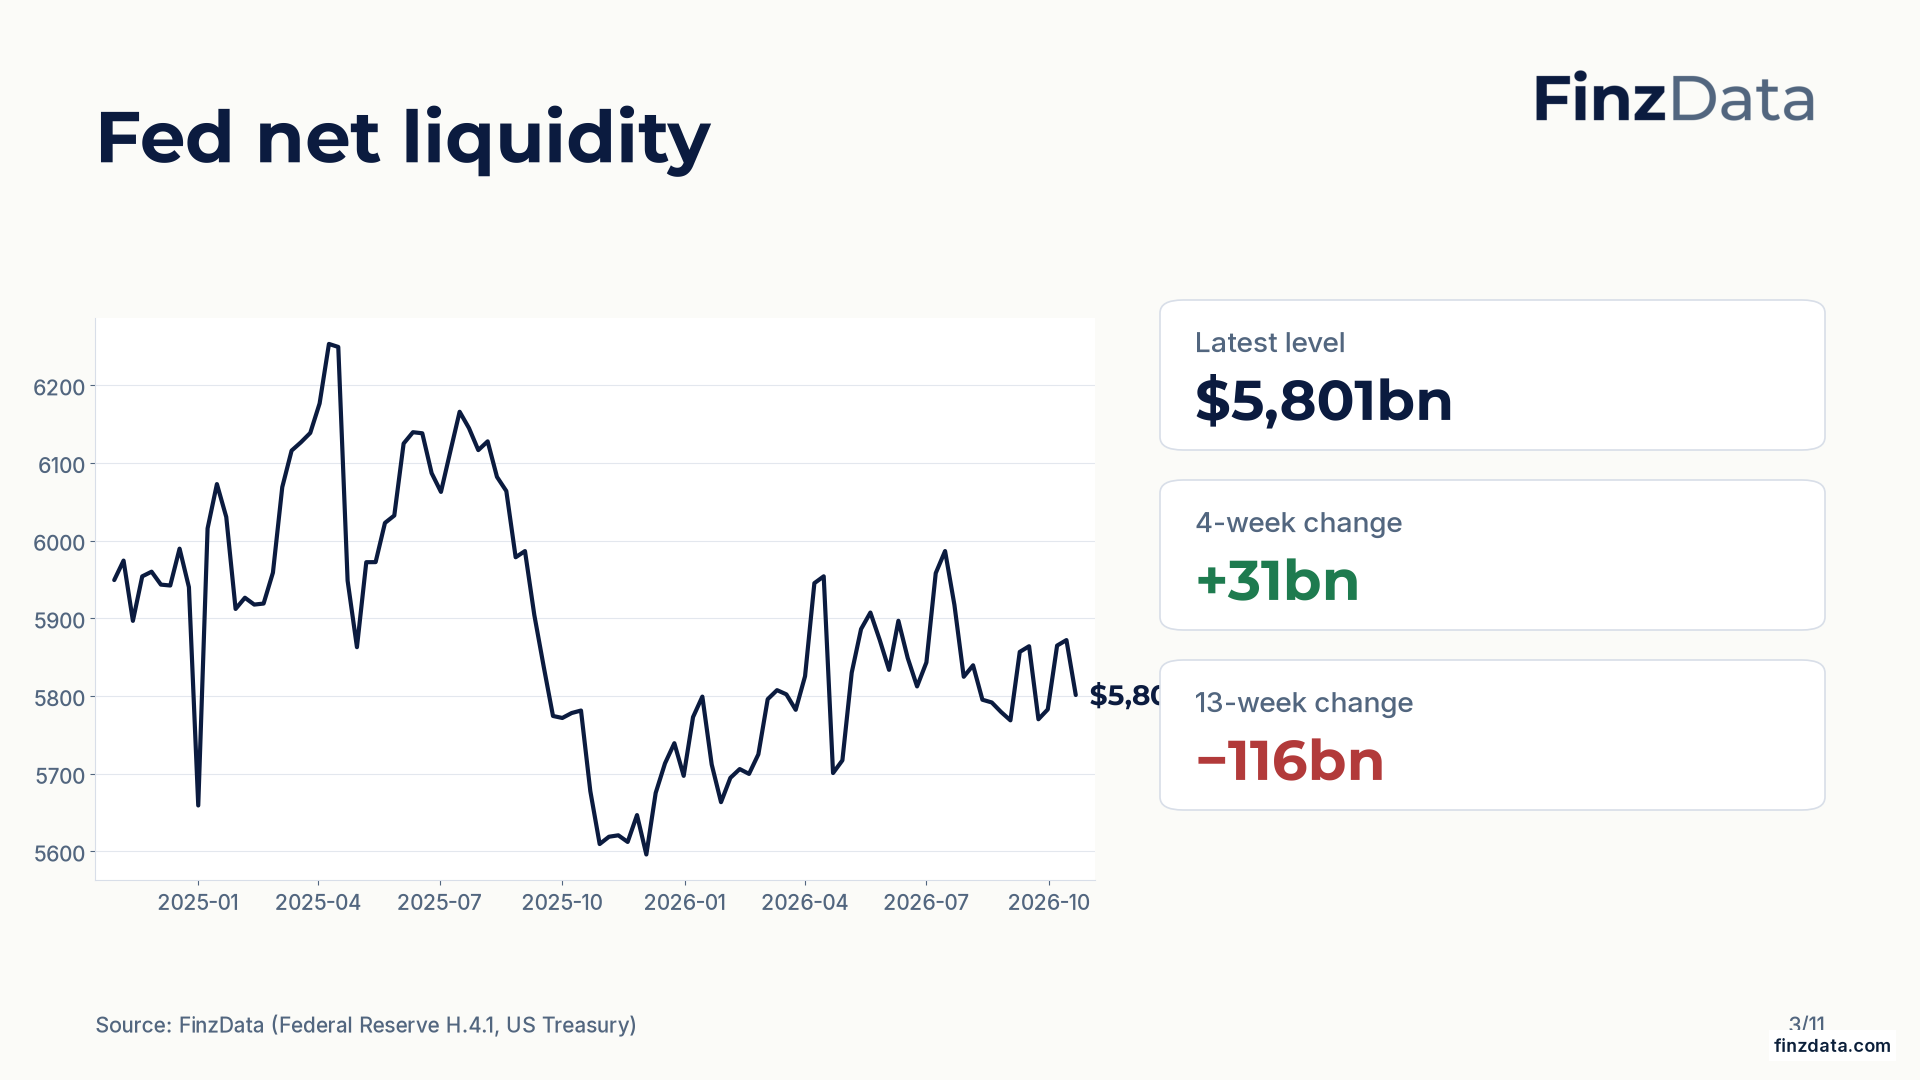
Fed net liquidity stands at $5,801bn as of 2026-10-21. The four-week change is +31bn and the thirteen-week change is −116bn.
| Series | Latest | As of | 1w | 4w | 13w | 1y |
|---|---|---|---|---|---|---|
| Fed net liquidity (assets − TGA − reverse repo) | $5,801bn | 2026-10-21 | −71bn | +31bn | −116bn | +20bn |
| Fed balance sheet | $6,754bn | 2026-10-21 | −2bn | +6bn | +6bn | +157bn |
| Treasury General Account | $952bn | 2026-10-21 | +69bn | −25bn | +122bn | +142bn |
| Overnight reverse repo | $0bn | 2026-10-21 | 0bn | 0bn | 0bn | −4bn |
| Bank reserves | $2,963bn | 2026-10-21 | −60bn | +32bn | −100bn | −56bn |
| M2 money supply (weekly) | $23,306bn | 2026-08-31 | +38bn | +97bn | +283bn | +1,333bn |
| Money market fund assets | $8,441bn | 2026-04-01 | +152bn | +152bn | +251bn | +960bn |
| G3 central bank assets (USD) | $17,524bn | 2026-09-01 | −124bn | −124bn | −235bn | −917bn |
| Chicago Fed financial conditions (NFCI) | -0.50 | 2026-10-16 | +0.01 | +0.03 | +0.04 | +0.03 |
| St. Louis Fed financial stress | -0.63 | 2026-10-16 | +0.09 | +0.07 | +0.07 | −0.15 |
Fed net liquidity is $5,801bn as of 2026-10-21 with a four-week change of +31bn. Treasury General Account is $952bn as of 2026-10-21 with a four-week change of −25bn.
4. What moved liquidity
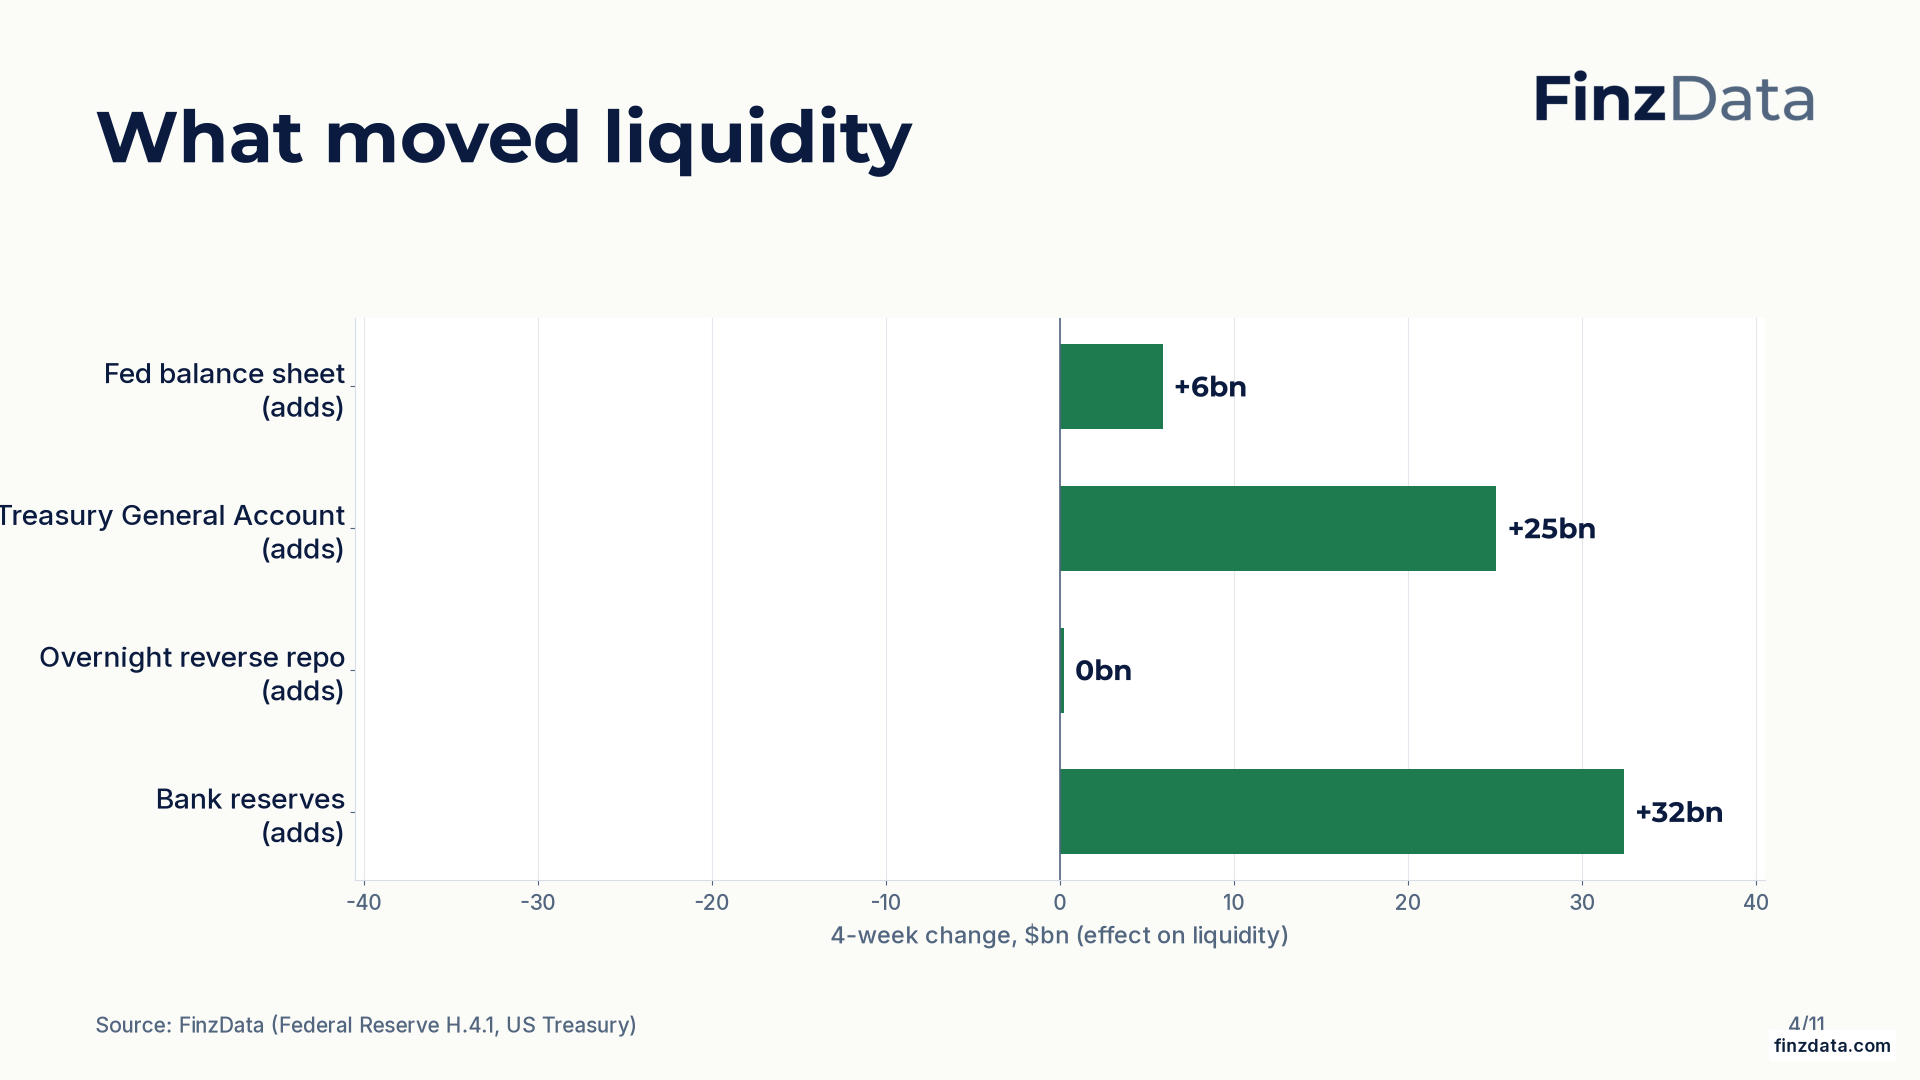
Four-week changes in the components of net liquidity: Fed balance sheet +6bn; Treasury General Account +25bn; Overnight reverse repo 0bn; Bank reserves +32bn.
5. Money and financial conditions
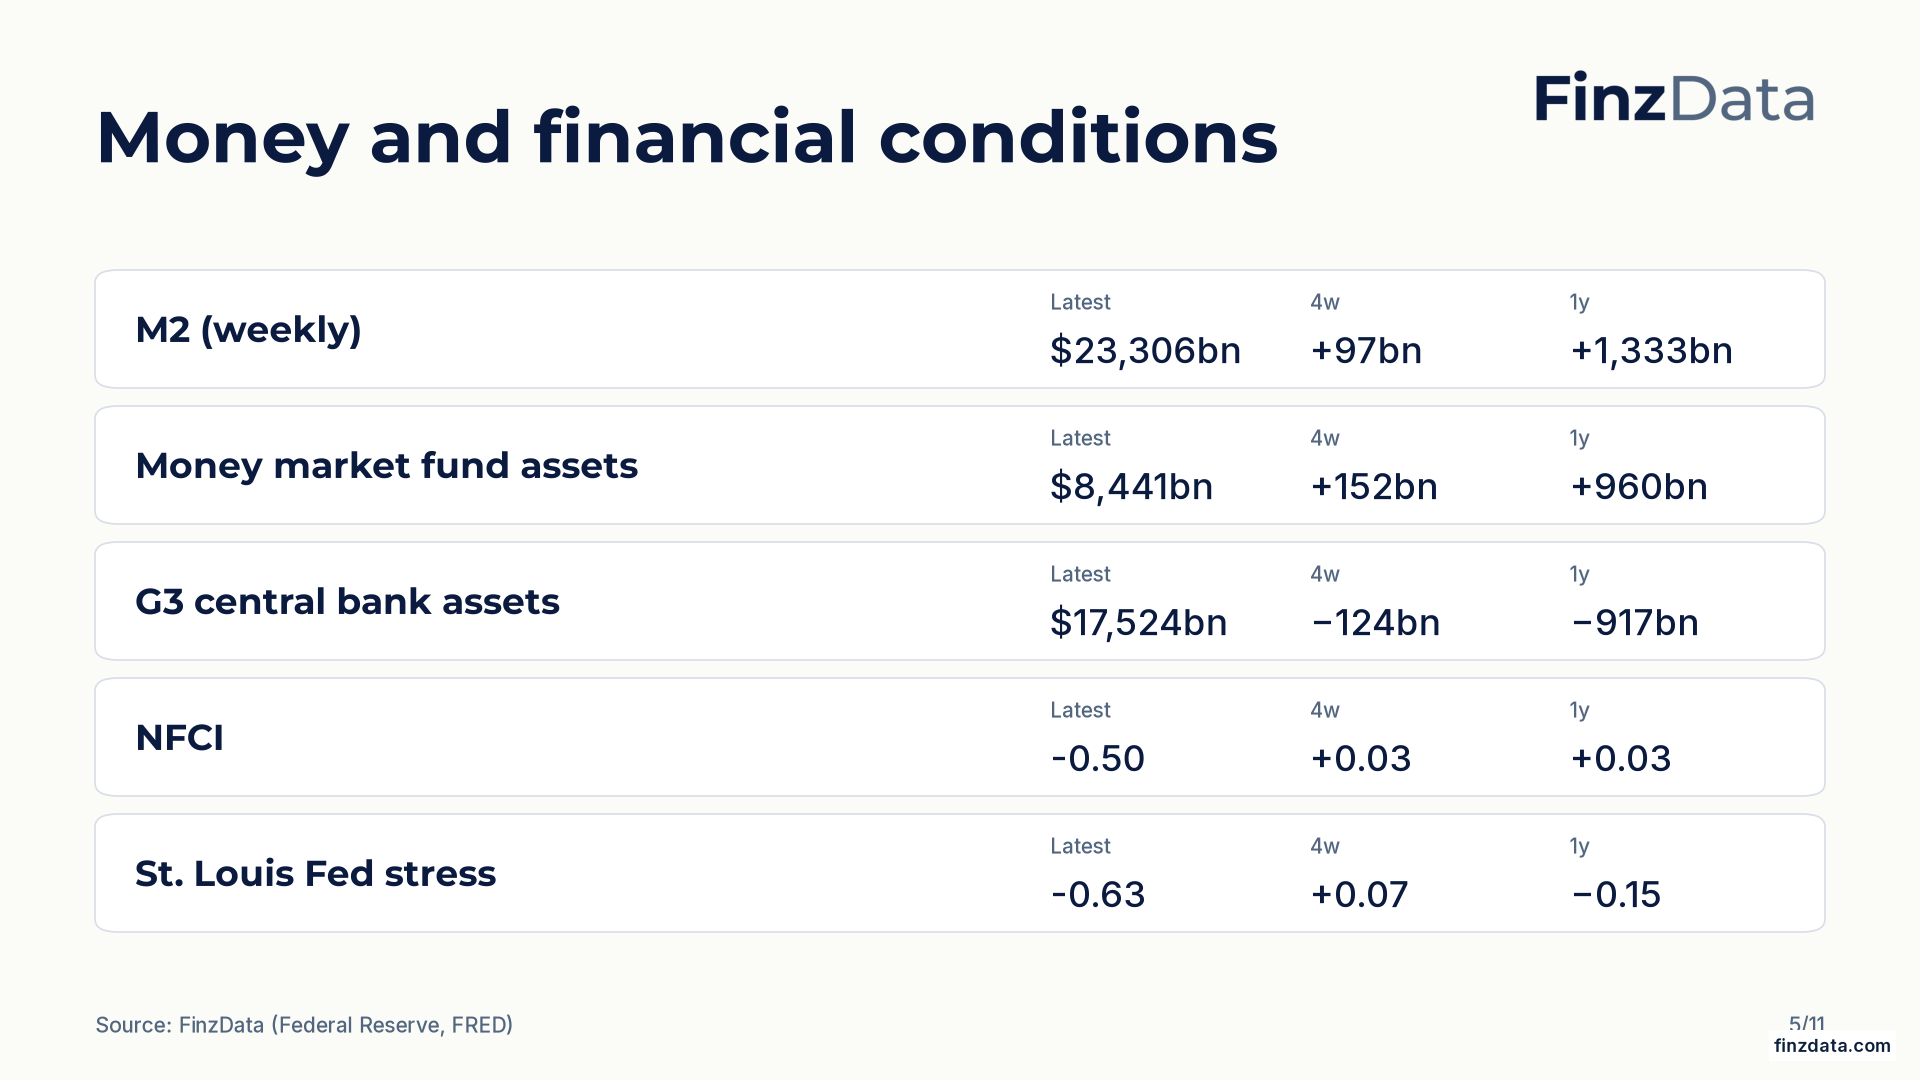
Money and financial conditions snapshot. For example, M2 (weekly) stands at $23,306bn as of 2026-08-31.
6. Foreign capital flows (TIC)
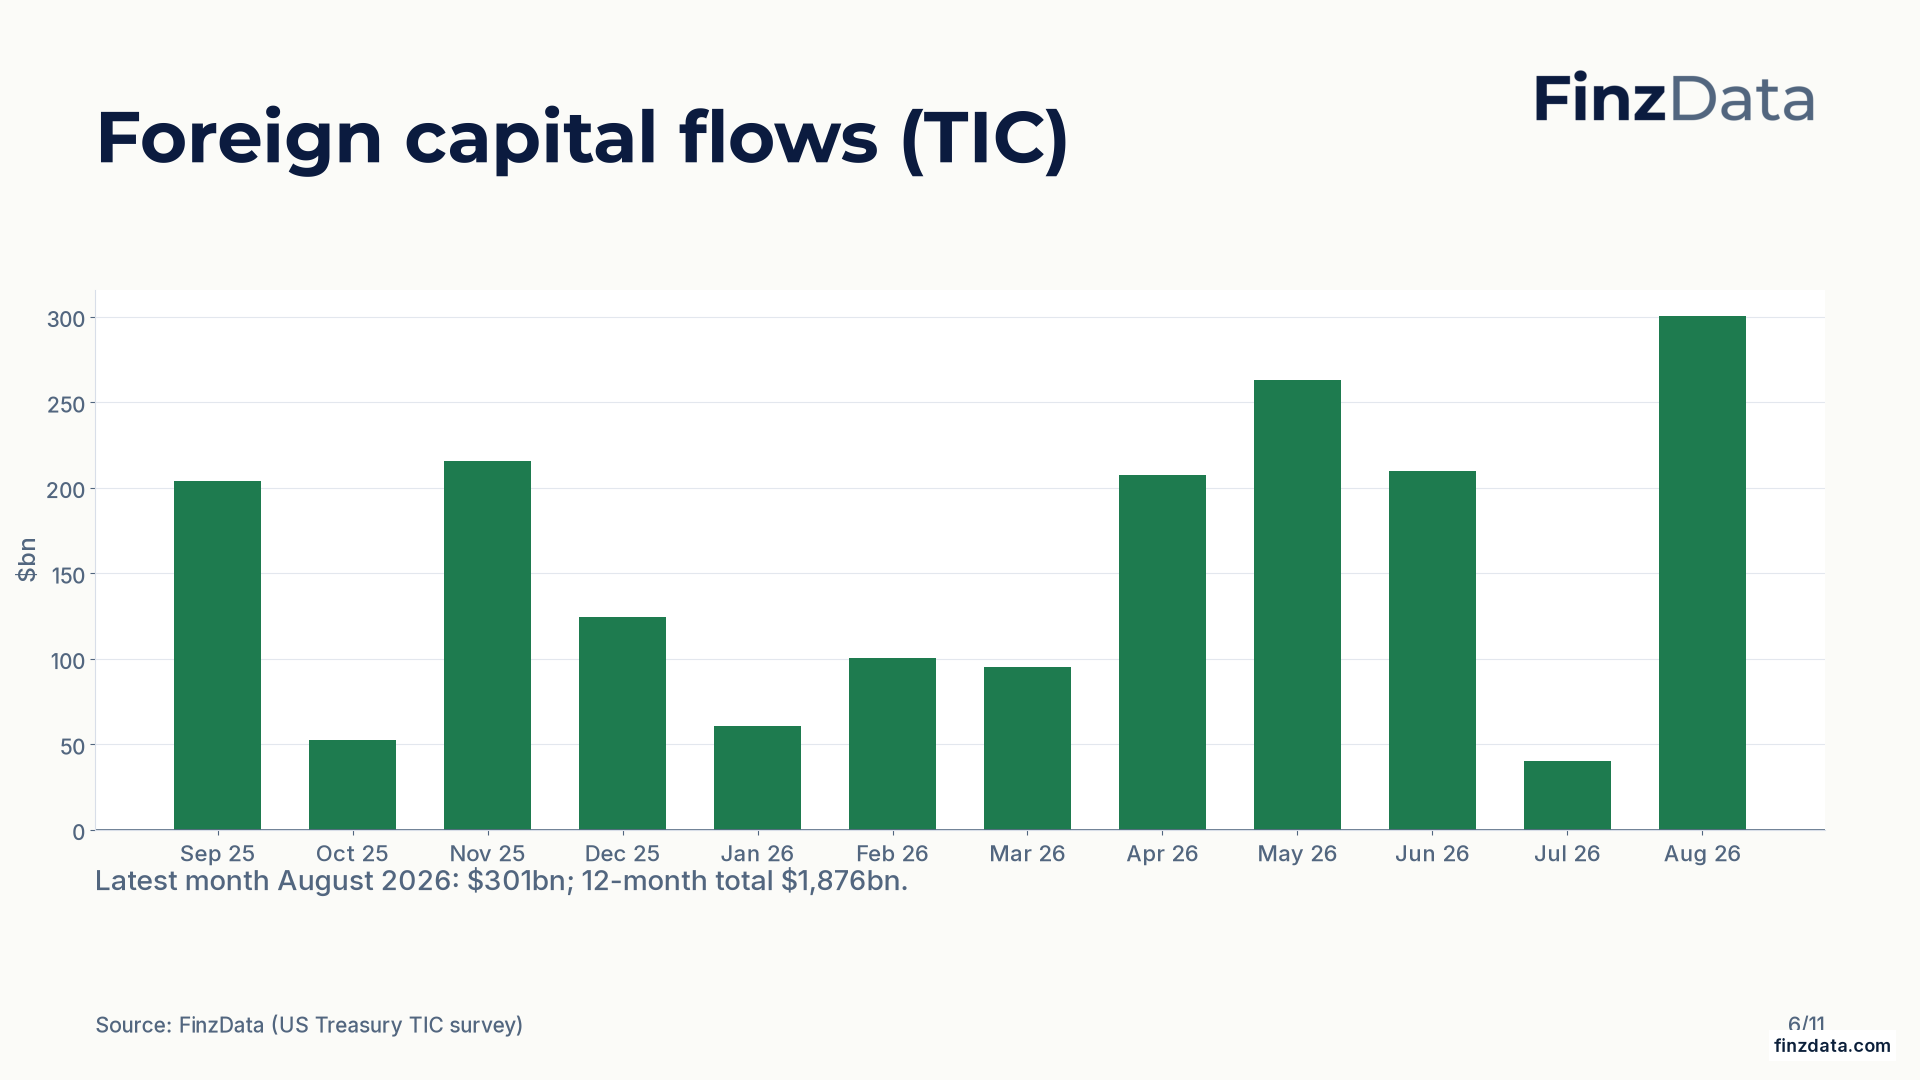
Net foreign purchases of US long-term securities over the last 12 months. Latest month August 2026: $301bn; 12-month total $1,876bn.
| Series | Latest month | Value | Prior month | 12-month total / change |
|---|---|---|---|---|
| Net foreign purchases of US long-term securities | 2026-08-01 | $301bn | $41bn | +1,876bn (12m total) |
| Net foreign purchases of US Treasuries | 2026-08-01 | $109bn | −$4bn | +306bn (12m total) |
| Foreign official net purchases of Treasuries | 2026-08-01 | $18bn | $26bn | +10bn (12m total) |
| Foreign holdings of US Treasuries | 2026-08-01 | $39,916bn | $38,826bn | +5,290bn (12m change) |
Net foreign purchases of US long-term securities were $301bn in 2026-08-01 with a 12-month total of +1,876bn. Net foreign purchases of US Treasuries were $109bn in 2026-08-01 with a 12-month total of +306bn.
7. ETF and crypto flows
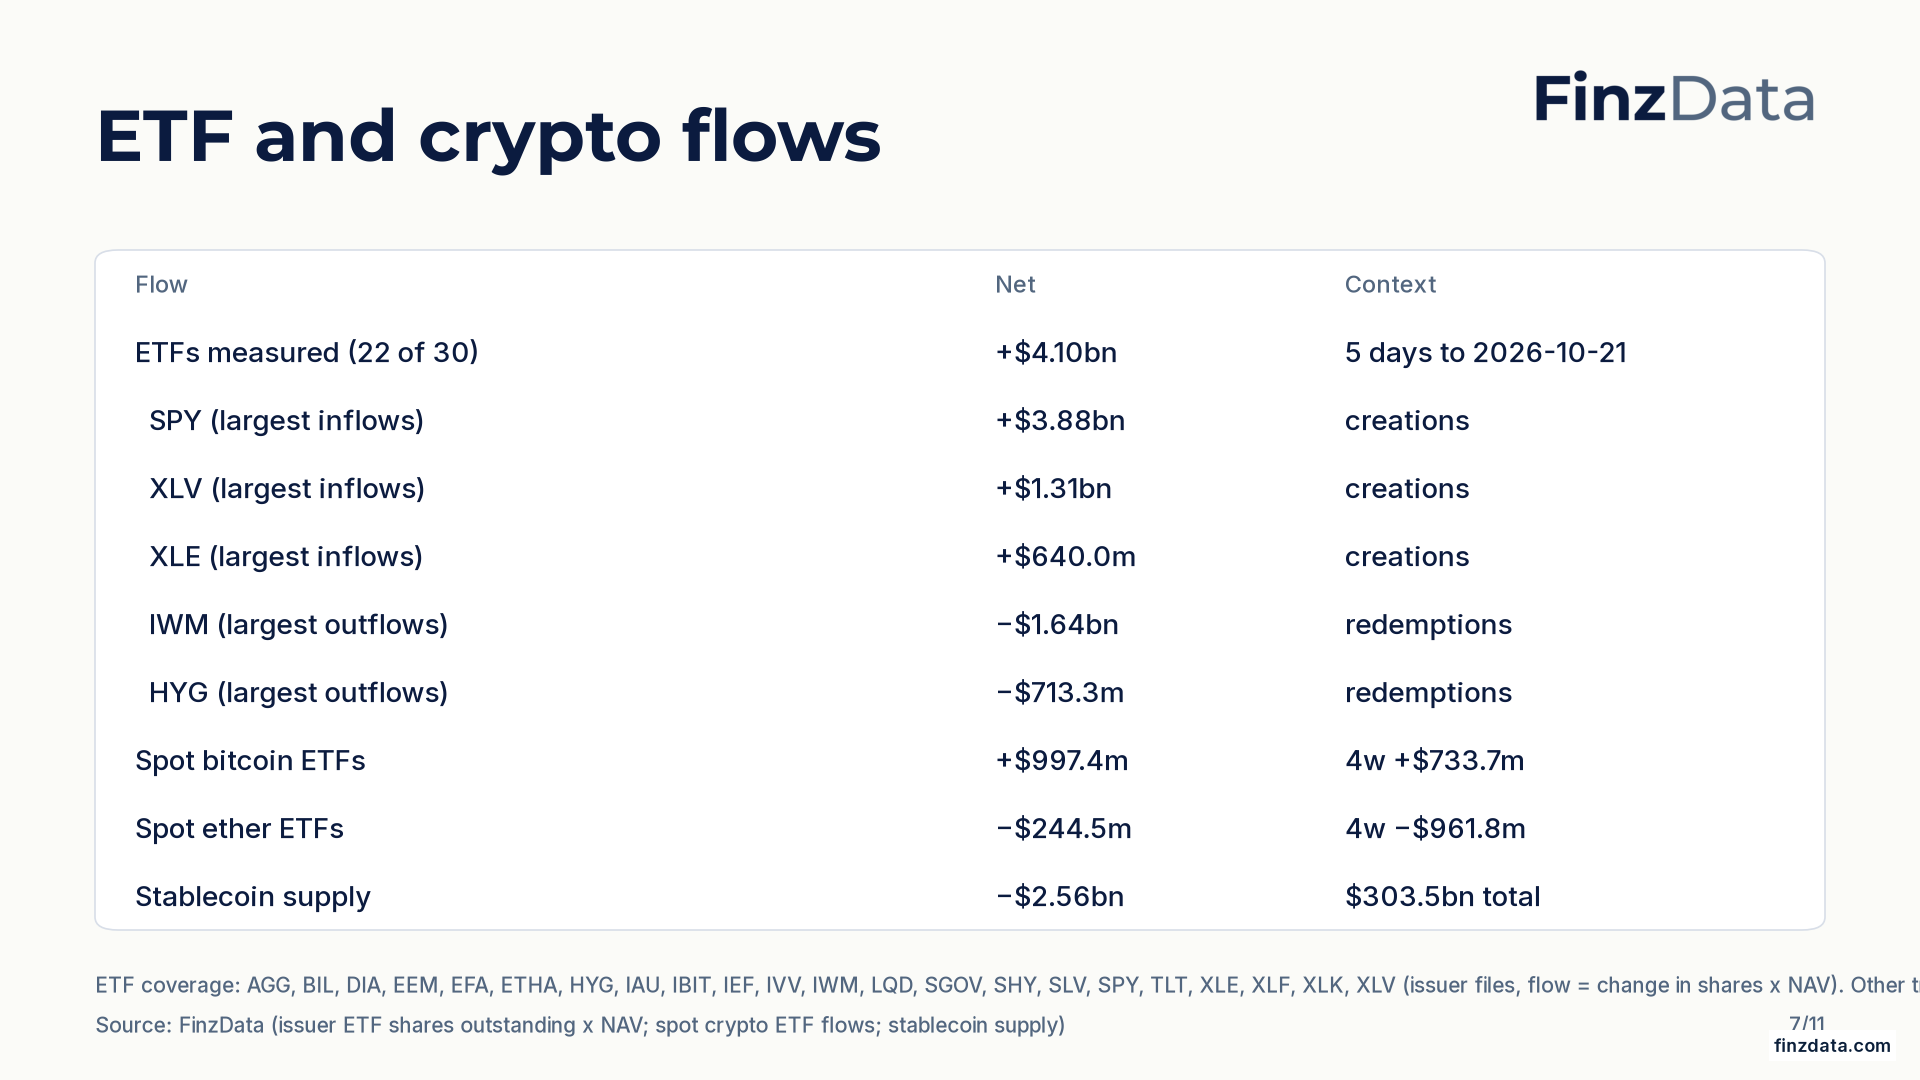
Net flow across the 22 of 30 tracked ETFs with issuer data this week: +$4.10bn. Not total US ETF flow. Spot bitcoin ETFs: +$997.4m over the week, +$733.7m over four weeks. Spot ether ETFs: −$244.5m over the week, −$961.8m over four weeks. USD stablecoin supply changed −$2.56bn over seven days to $303.5bn.
US-listed ETF creations and redemptions
Net flow across the funds we measure this week: +$4.10bn (5 trading days to 2026-10-21; flow = change in shares outstanding x NAV, from the issuers' own daily files). Coverage this week: 22 of 30 tracked funds (AGG, BIL, DIA, EEM, EFA, ETHA, HYG, IAU, IBIT, IEF, IVV, IWM, LQD, SGOV, SHY, SLV, SPY, TLT, XLE, XLF, XLK, XLV); the rest are not yet measured, so this is not total US ETF flow.
| Asset class | Net flow (week) |
|---|---|
| Sector | +$1.92bn |
| US equity | +$1.46bn |
| Treasuries | +$736.9m |
| Crypto | +$428.3m |
| Gold & metals | +$128.9m |
| International equity | $0.0m |
| Credit | −$569.0m |
| ETF | Fund | Net flow (week) |
|---|---|---|
| SPY | SPY | +$3.88bn |
| XLV | XLV | +$1.31bn |
| XLE | XLE | +$640.0m |
| IBIT | IBIT | +$628.4m |
| SGOV | SGOV | +$603.6m |
| IWM | IWM | −$1.64bn |
| HYG | HYG | −$713.3m |
| IVV | IVV | −$467.5m |
| IEF | IEF | −$370.1m |
| DIA | DIA | −$308.7m |
Crypto flows
| Series | 1 week | 4 weeks | Latest | Largest in / out |
|---|---|---|---|---|
| Spot bitcoin ETFs | +$997.4m | +$733.7m | 2026-10-21 | IBIT +$875.1m, GBTC −$22.3m |
| Spot ether ETFs | −$244.5m | −$961.8m | 2026-10-21 | ETH +$31.4m, ETHA −$271.8m |
| Stablecoin supply (USD-pegged) | −$2.56bn | −$1.59bn | 2026-10-21 | $303.5bn outstanding |
8. Positioning map
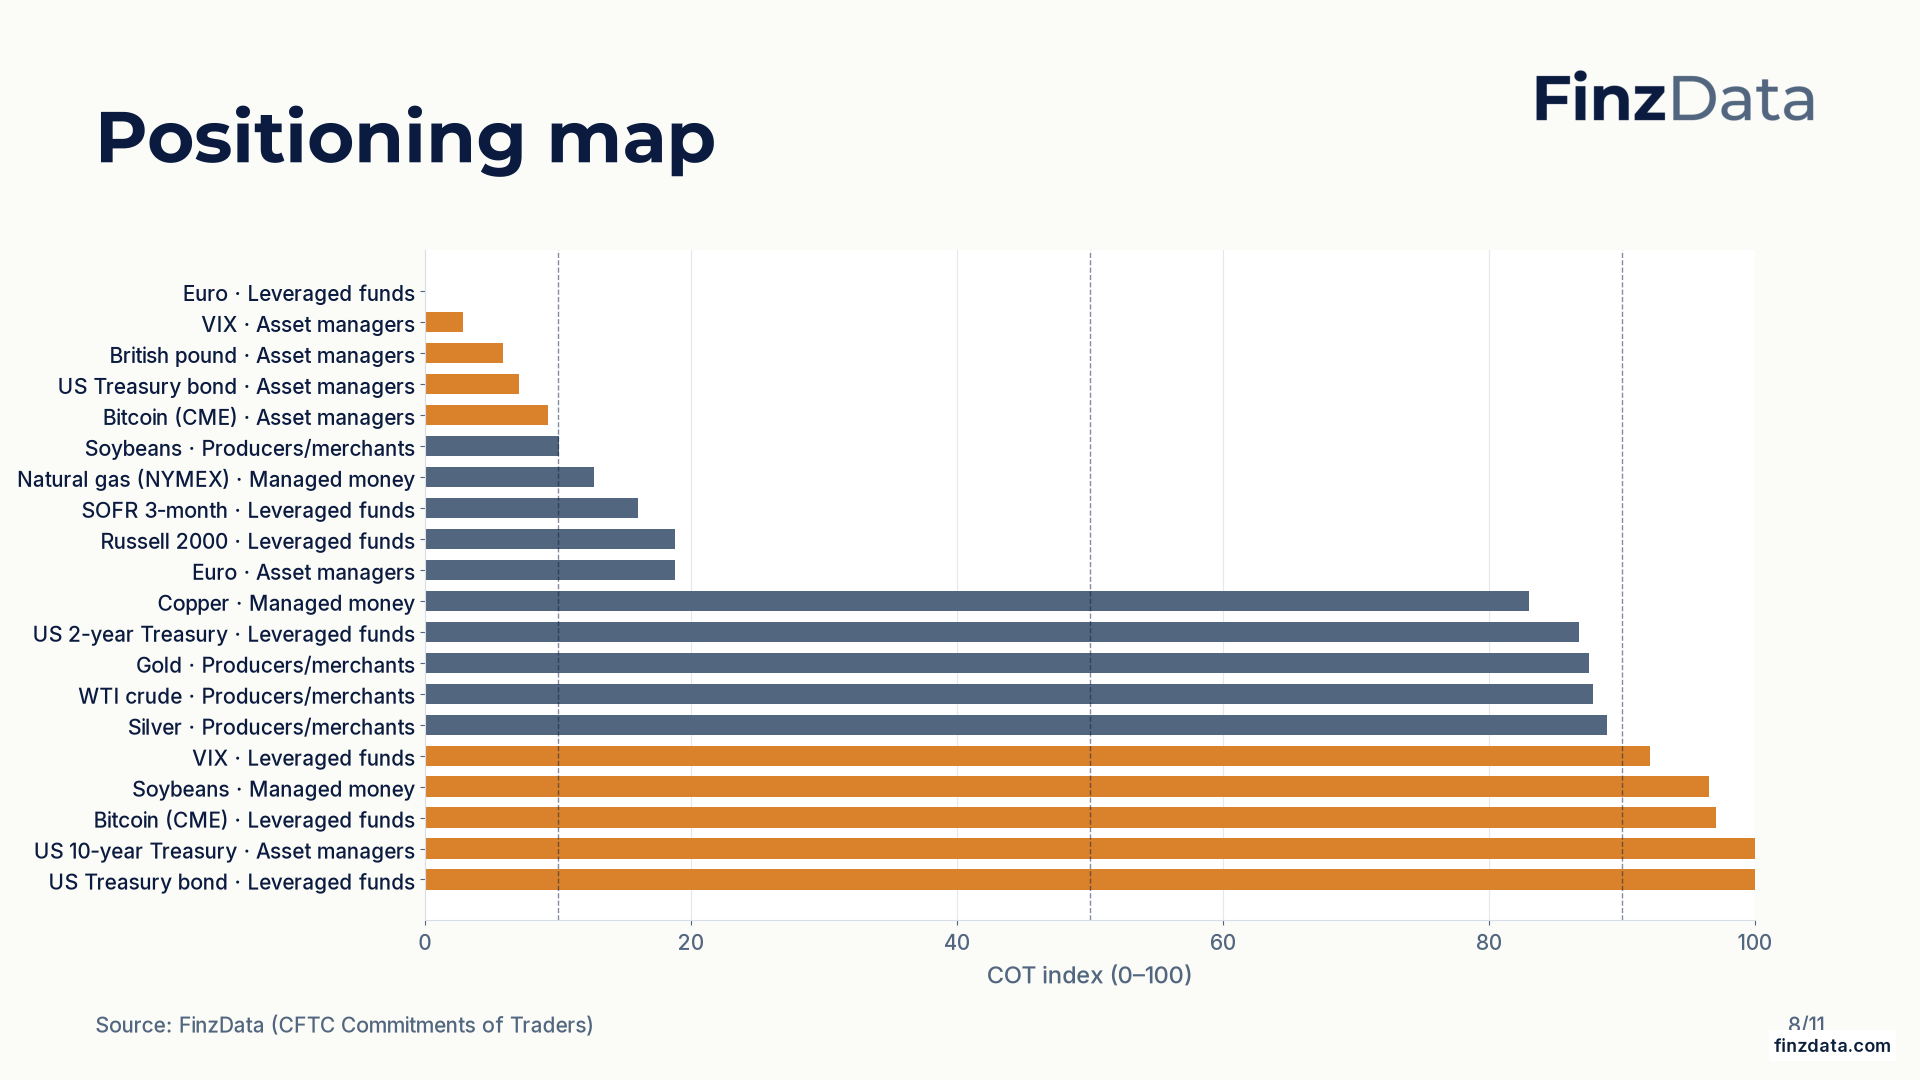
COT index for every tracked market and trader group. Highest reading: US 10-year Treasury (Asset managers) at 100; lowest: Euro (Leveraged funds) at 0.
TFF report (financial futures)
| Market | Group | Net contracts | Net % OI | w/w pp | COT index | Percentile | Flag |
|---|---|---|---|---|---|---|---|
| S&P 500 | Asset managers | 918,097 | 47.1% | +0.5pp | 62 | 94% | |
| S&P 500 | Leveraged funds | -410,518 | -21.1% | +0.3pp | 33 | 3% | |
| Nasdaq-100 | Asset managers | 76,402 | 25.9% | +0.8pp | 64 | 69% | |
| Nasdaq-100 | Leveraged funds | -21,891 | -7.4% | +1.6pp | 68 | 35% | |
| Russell 2000 | Asset managers | 29,528 | 6.6% | −4.1pp | 26 | 47% | |
| Russell 2000 | Leveraged funds | -91,647 | -20.6% | +4.2pp | 19 | 5% | |
| VIX | Asset managers | -77,295 | -17.2% | +1.0pp | 3 | 0% | Crowded short |
| VIX | Leveraged funds | 1,105 | 0.2% | −1.0pp | 92 | 93% | Crowded long |
| US 2-year Treasury | Asset managers | 1,795,866 | 39.4% | +2.0pp | 45 | 85% | |
| US 2-year Treasury | Leveraged funds | -1,367,408 | -30.0% | −2.0pp | 87 | 26% | |
| US 10-year Treasury | Asset managers | 2,898,562 | 49.8% | +0.6pp | 100 | 100% | Crowded long |
| US 10-year Treasury | Leveraged funds | -2,205,937 | -37.9% | −0.6pp | 22 | 7% | |
| US Treasury bond | Asset managers | 391,534 | 21.2% | −0.2pp | 7 | 37% | Crowded short |
| US Treasury bond | Leveraged funds | -154,020 | -8.3% | +1.7pp | 100 | 59% | Crowded long |
| SOFR 3-month | Asset managers | -466,919 | -3.6% | +0.2pp | 25 | 26% | |
| SOFR 3-month | Leveraged funds | -2,245,507 | -17.4% | +1.2pp | 16 | 6% | |
| Euro | Asset managers | 199,918 | 22.9% | +1.0pp | 19 | 46% | |
| Euro | Leveraged funds | -68,001 | -7.8% | −2.7pp | 0 | 43% | Crowded short |
| Japanese yen | Asset managers | 65,819 | 17.6% | −0.8pp | 73 | 74% | |
| Japanese yen | Leveraged funds | -33,673 | -9.0% | −2.2pp | 53 | 60% | |
| British pound | Asset managers | -145,735 | -54.3% | +0.4pp | 6 | 0% | Crowded short |
| British pound | Leveraged funds | 10,313 | 3.8% | −0.8pp | 23 | 45% | |
| Bitcoin (CME) | Asset managers | 3,642 | 17.6% | +1.1pp | 9 | 46% | Crowded short |
| Bitcoin (CME) | Leveraged funds | -5,844 | -28.2% | +3.8pp | 97 | 67% | Crowded long |
Disaggregated report (commodities)
| Market | Group | Net contracts | Net % OI | w/w pp | COT index | Percentile | Flag |
|---|---|---|---|---|---|---|---|
| WTI crude | Managed money | 40,574 | 2.1% | −0.7pp | 27 | 3% | |
| WTI crude | Producers/merchants | 353,143 | 18.6% | +0.9pp | 88 | 99% | |
| Natural gas (NYMEX) | Managed money | -126,481 | -7.3% | +0.7pp | 13 | 28% | |
| Natural gas (NYMEX) | Producers/merchants | -10,881 | -0.6% | −0.2pp | 74 | 83% | |
| Gold | Managed money | 107,089 | 27.0% | −1.0pp | 39 | 61% | |
| Gold | Producers/merchants | -18,437 | -4.7% | +0.3pp | 87 | 94% | |
| Silver | Managed money | 5,619 | 5.2% | −2.0pp | 25 | 24% | |
| Silver | Producers/merchants | -15,801 | -14.6% | +0.9pp | 89 | 87% | |
| Copper | Managed money | 61,058 | 19.5% | −0.7pp | 83 | 78% | |
| Copper | Producers/merchants | -90,466 | -28.8% | +1.7pp | 23 | 36% | |
| Corn | Managed money | 246,425 | 13.4% | −4.4pp | 78 | 68% | |
| Corn | Producers/merchants | -600,489 | -32.5% | +4.5pp | 24 | 28% | |
| Soybeans | Managed money | 249,807 | 23.3% | +0.3pp | 97 | 90% | Crowded long |
| Soybeans | Producers/merchants | -302,978 | -28.3% | −0.5pp | 10 | 40% |
Crowding and weekly swings
Most crowded (by |COT index − 50|)
- US 10-year Treasury (Asset managers): COT index 100, flag: Crowded long.
- US Treasury bond (Leveraged funds): COT index 100, flag: Crowded long.
- Euro (Leveraged funds): COT index 0, flag: Crowded short.
- VIX (Asset managers): COT index 3, flag: Crowded short.
- Bitcoin (CME) (Leveraged funds): COT index 97, flag: Crowded long.
Largest weekly swings (by |w/w pp|)
- Corn (Producers/merchants): +4.5pp to -32.5% of open interest.
- Corn (Managed money): −4.4pp to 13.4% of open interest.
- Russell 2000 (Leveraged funds): +4.2pp to -20.6% of open interest.
- Russell 2000 (Asset managers): −4.1pp to 6.6% of open interest.
- Bitcoin (CME) (Leveraged funds): +3.8pp to -28.2% of open interest.
Most crowded COT index is 100 for US 10-year Treasury Asset managers and US Treasury bond Leveraged funds. Largest weekly swing in net % of open interest is Corn Producers/merchants at +4.5pp.
9. Most crowded
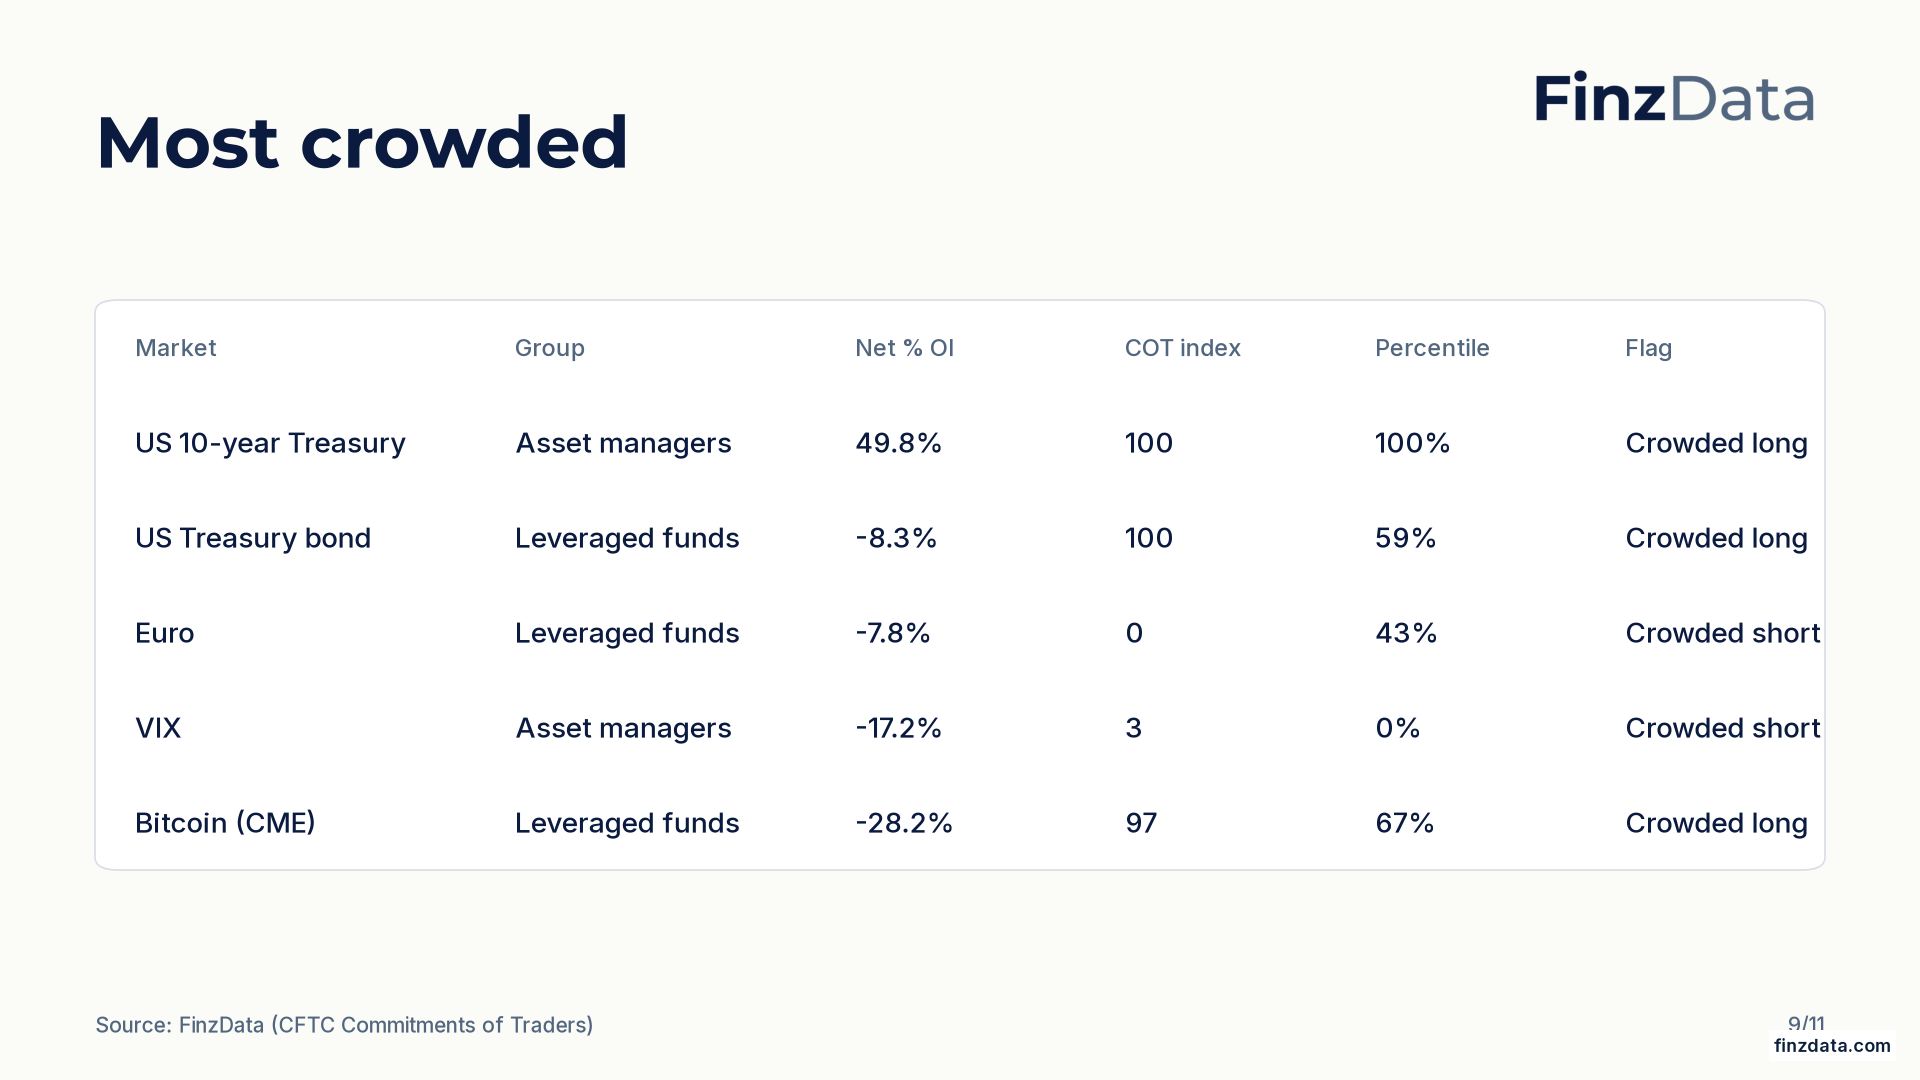
Most crowded positioning by distance of the COT index from 50. Top of the list: US 10-year Treasury (Asset managers) with a COT index of 100 and net 49.8% of open interest.
10. Biggest weekly swings
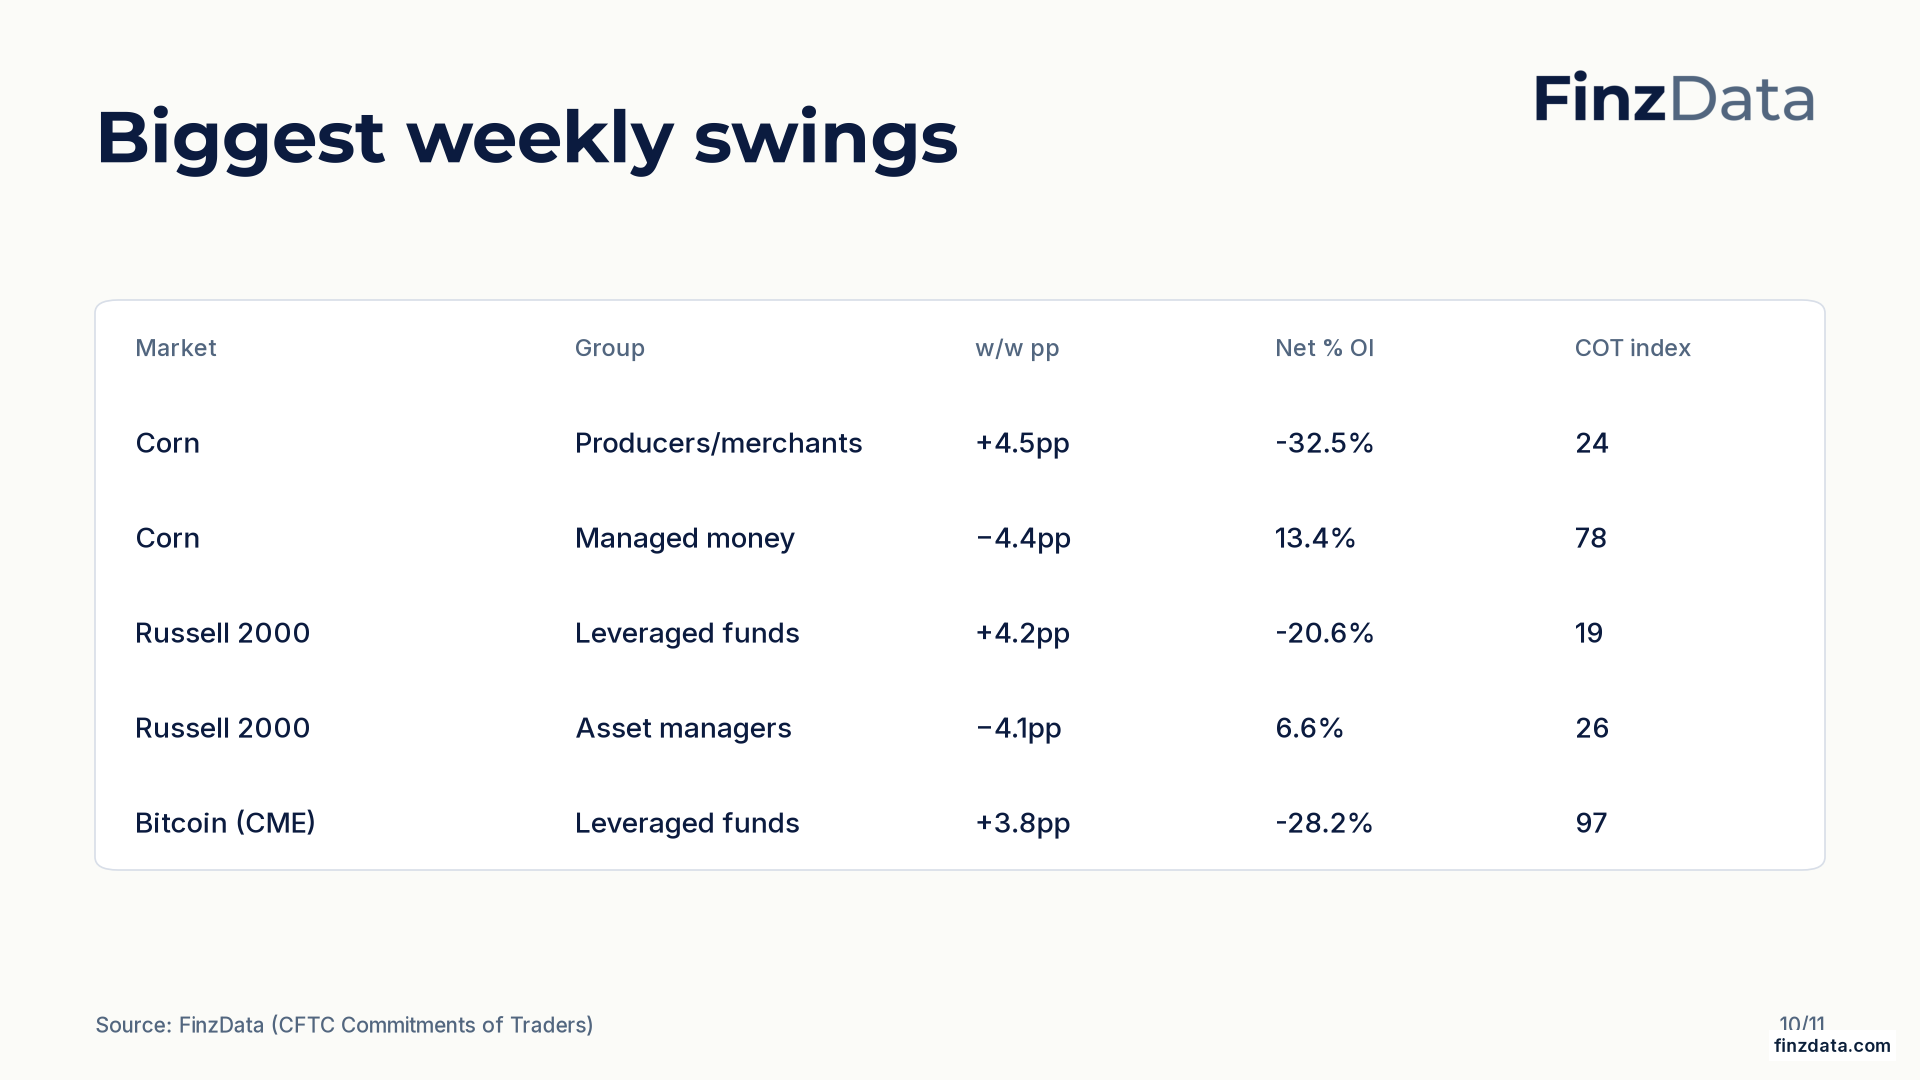
Largest weekly swings in net percent of open interest. Biggest move: Corn (Producers/merchants) at +4.5pp to -32.5% of open interest.
11. Every number here is one call to the FinzData API
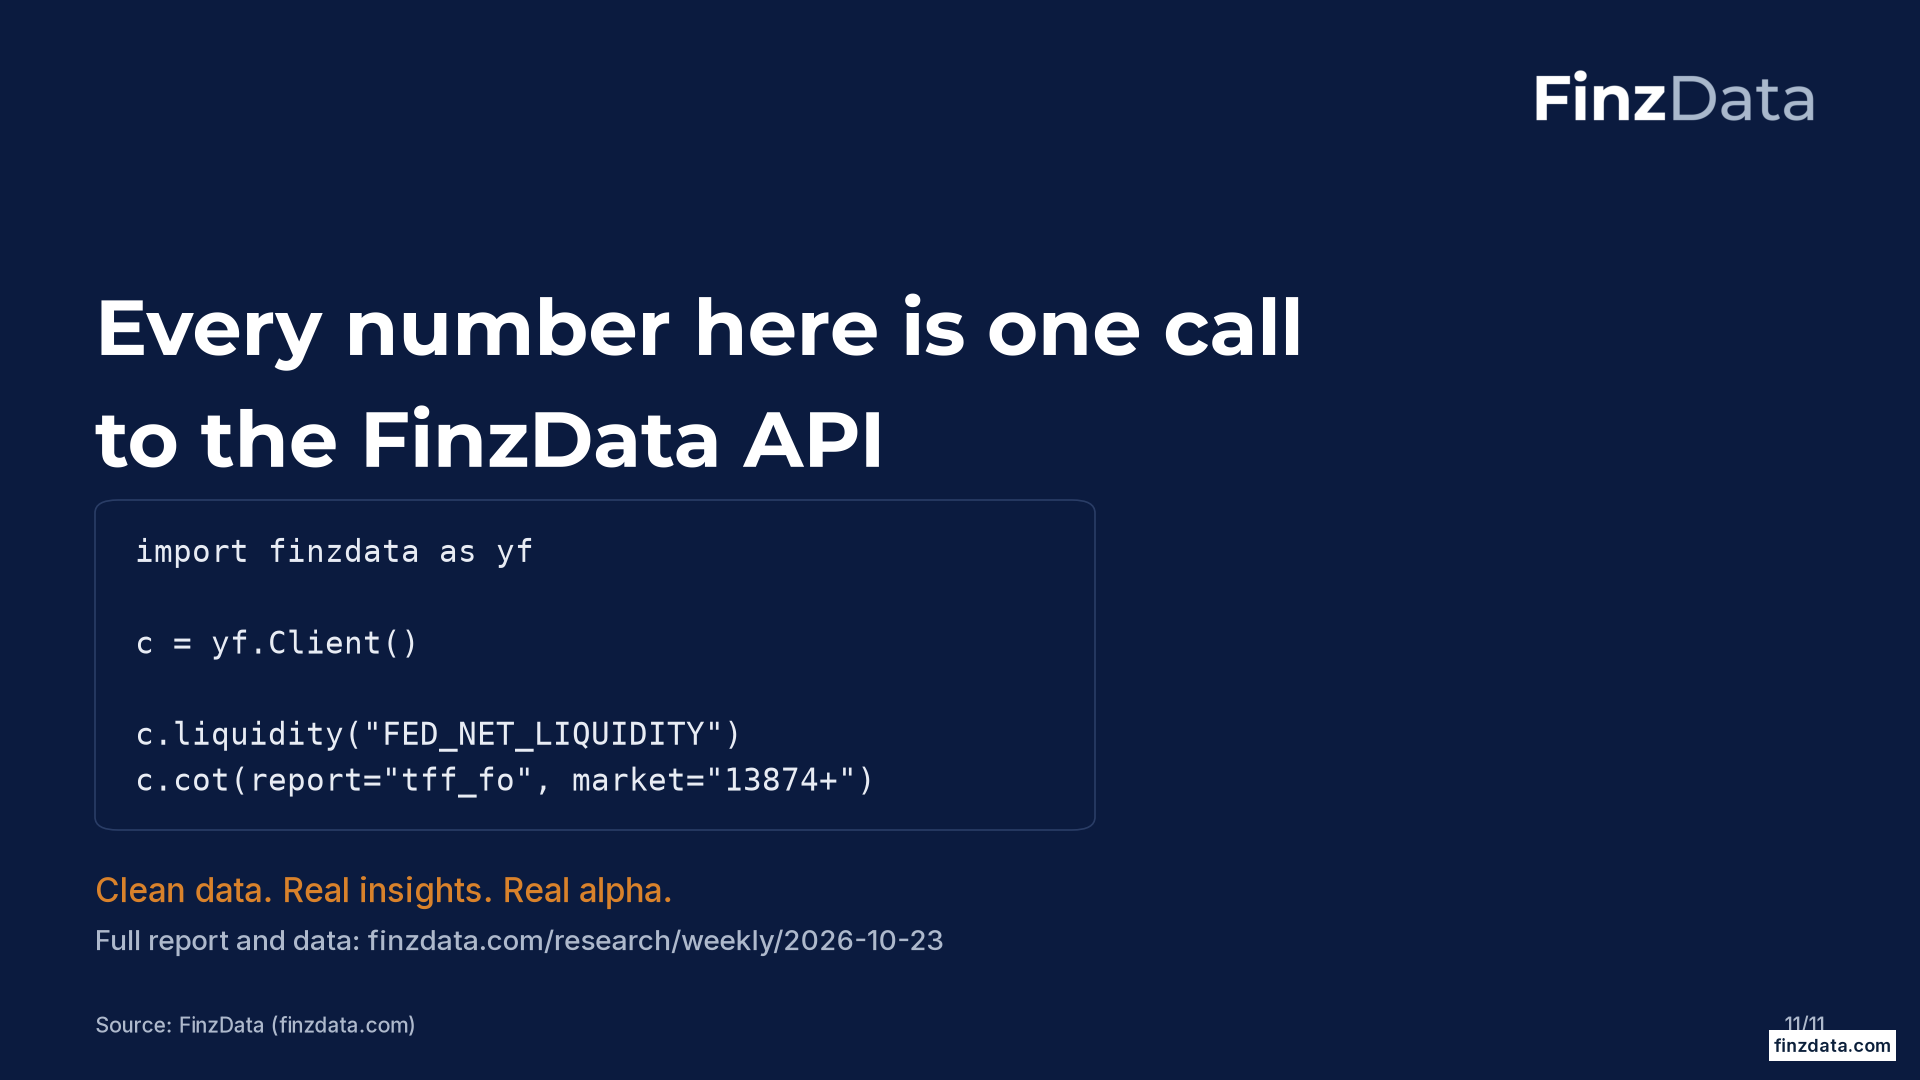
Closing slide. Every figure in this deck is available through the FinzData API; the full report is at finzdata.com/research/weekly/2026-10-23.
Method and sources
All figures are point-in-time for the issue date. COT positioning uses rows dated on or before issue date minus four days (Tuesday positions published the following Friday). Liquidity and TIC series use rows dated on or before issue date minus two days. This lets us rebuild past issues exactly as they would have appeared at the time.
- Liquidity and flows: latest observation, plus the change versus the last observation on or before 7, 28, 91 and 365 calendar days earlier. Monthly TIC flows also show the prior month and a trailing-12-month sum; foreign holdings show the level and the 12-month change.
- Positioning: net = long − short contracts per trader group; net % of open interest = 100 × net ÷ total open interest; w/w change in net contracts and in net % of open interest (percentage points); COT index = 100 × (net − min) ÷ (max − min) over the last 156 weekly rows (50 when max equals min); percentile of net % of open interest versus all history since 2010. "Crowded long" when the COT index is 90 or above, "Crowded short" when 10 or below.
- Sources: Federal Reserve H.4.1, US Treasury, FRED, CFTC Commitments of Traders, and the US Treasury TIC survey, all stored in the FinzData database.
Explore the underlying series: COT positioning, datasets, explore, and the RSS feed.
Download the deck (PDF, 11 slides) PowerPoint · CSV · JSON
Get a free API key All weekly issues · RSS · More research
Built for AI, quants, data scientists and financial analysts who backtest. Clean data. Real insights. Real alpha. finzdata.com. This material is for information only and is not investment advice.
Get FinzData research free, every morning
The daily brief: what moved, the macro releases that matter, positioning and liquidity, with charts. One email a day, free, unsubscribe anytime.